Home › Forums › Open Trades › Upside Fly in RUT
- This topic has 0 replies, 1 voice, and was last updated 10 years ago by
Steven Place.
-
AuthorPosts
-
November 7, 2016 at 11:01 am #7175
Steven Place
KeymasterTwo things I’m looking at on the RUT 2000:
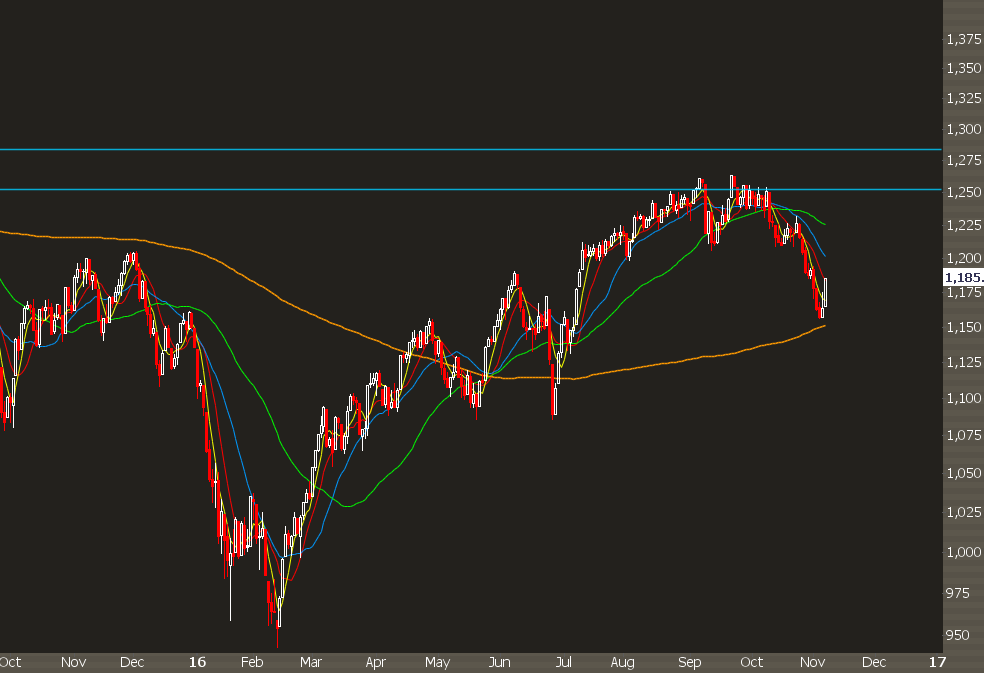
First is the price action. While the S&P has been a slow bleed lower, the Russell got properly oversold. Today we’re seeing a pretty solid gap up, and while I think the gap higher is suspect, we’ve seen enough selling to say that a bounce is due.
Now in terms of catalysts… we’ve got the election that I honestly think is a nonissue (people just using it as an excuse to sell) and we’ve got the December rate hike which has already begun to get priced in.
Now the Russell is a bunch of small cap companies, and many don’t have dividends… it’s not a very rate sensitive market. So if/when the Fed hikes it won’t be a huge deal.
Next up:
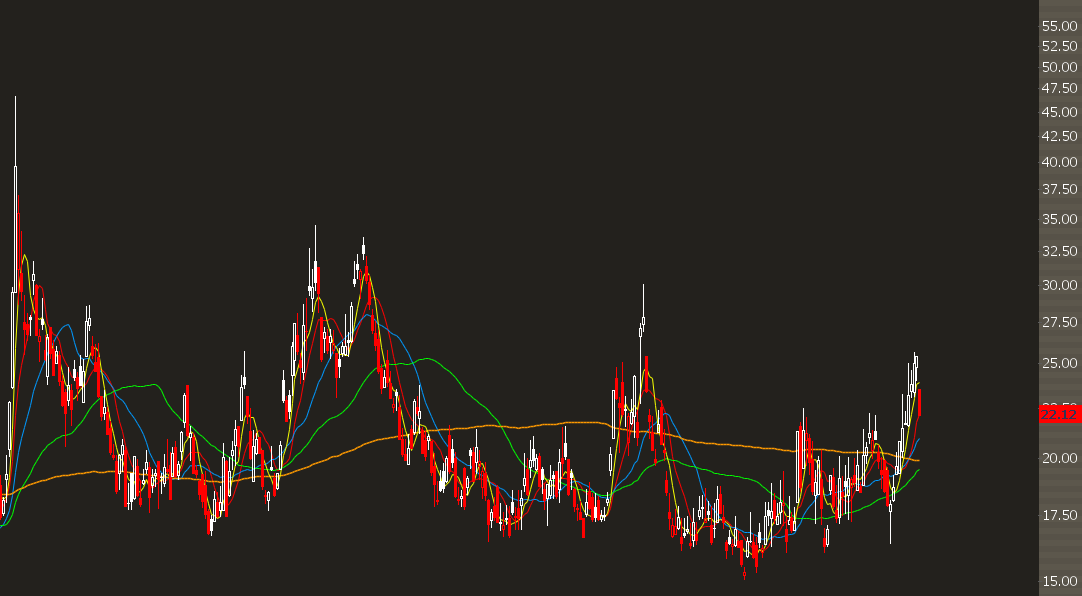
This is chart of the RVX, which is the VIX for the Russell 2k.
If we are in bounce mode, this will probably pull in a good amount.
Think about it… 30 days out, we’ve got the Fed decision and that’s basically it into the end of the year.
And if we look at Jan options… the Jan options have a full holiday schedule with historicailly low actual vol.
So we can place a bet looking for upside drift and the market to pull in the vol.
This is where call butterflies make a lot of sense.
Now look, this is going to seem a little complex but it will make sense in the end.
This is a broken wing butterfly.
IWO Premium Order Ticket Type Asset Duration Strike C/P BTO RUT 20 Jan 17 1310 Call STO 2x RUT 20 Jan 17 1230 Call BTO RUT 20 Jan 17 1180 Put Total Debit: 8.7 Here’s what the trade looks like:
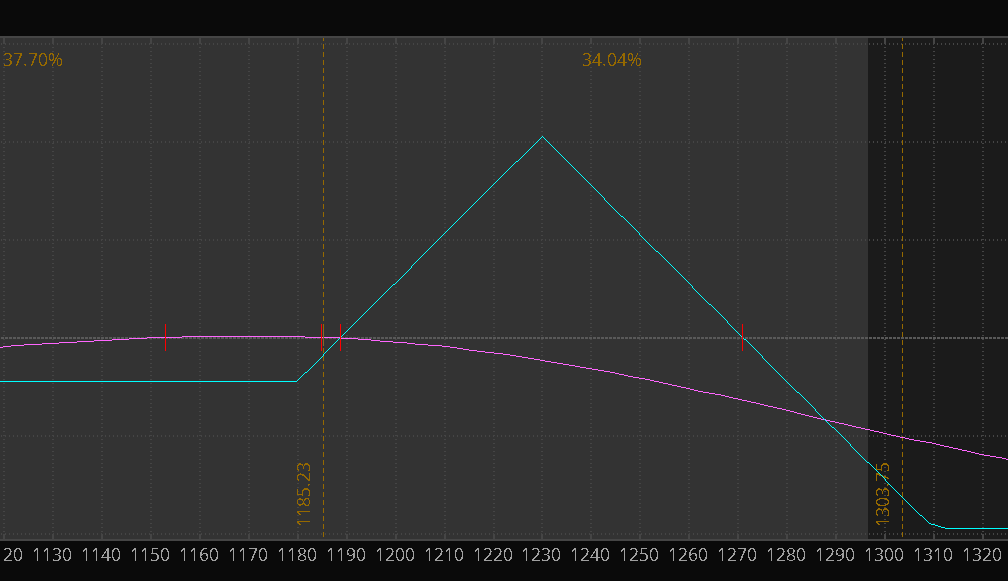
Ok so the ideal scenario is a drift higher as vol pulls in. What will happen here is that as we drift higher and the holiday season approaches, then we will the short options decay pretty fast while our long options, especialily the 1180 call, appreciates in value.
Basically, if we come into 1220 and vol drops 3%, here’s what the position will look like in a week:
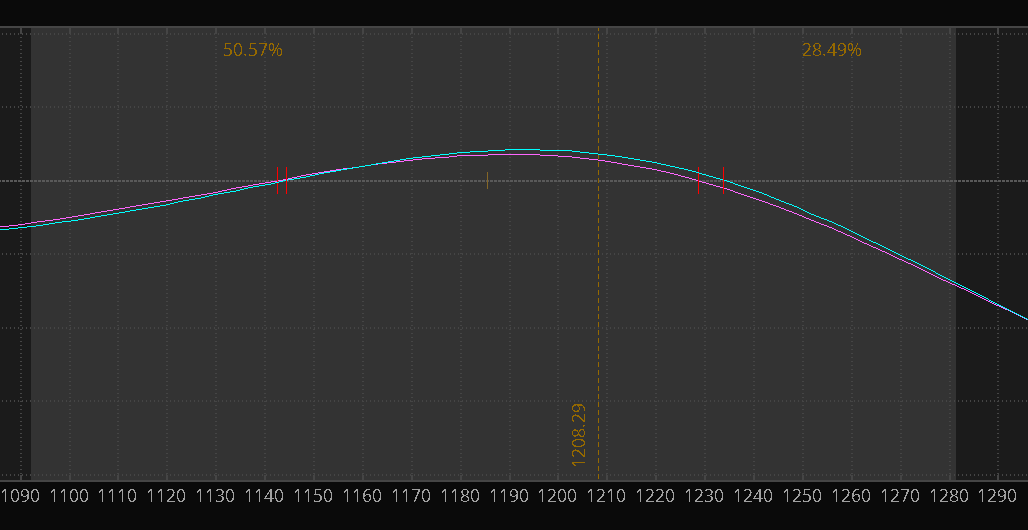
Now I think that P/L is generous, but that theme makes sense.
So in terms of adverse outcomes… the worst case scenario here is a massive rip higher with no pullback.
The RUT would have to break to new all time highs within a month. I don’t think that’s very high odds. But it’s possible. So if 1230 is cleared, we’ll buy some calls to reduce the short delta in the position.
The second scenario here is if the market were to drop even further. This is a much easier fix.
If the market drops, we will buy call spreads. What this will do is effectively roll the lower call down further… eventually it will convert this into a regular butterfly. By adding more capital we will reduce our delta (directional exposure) and increase the breakevens and increase the theta.
Our goal is a 15% return on total capital involved.
Attachments:
You must be logged in to view attached files. -
AuthorPosts
- You must be logged in to reply to this topic.